Do You Really Need Critical Illness Insurance?
We buy insurance because we want to feel protected.
Protected if we get sick.
Protected if we can't work.
Protected if one of those big, horrible, life-changing things happens that we'd really rather not think about.
And that makes perfect sense.
But are we buying insurance simply because something might happen, without stopping to ask what financial problem we're actually trying to protect ourselves from?
Critical illness insurance - also known as dread disease cover, is a good example.
You pay a premium, and if you're diagnosed with one of the qualifying illnesses and meet the policy conditions, you receive a lump-sum payout.
I call it "illness bingo."
You get this illness? Here's your payout.
But before deciding whether you need critical illness cover, or whether you should keep paying for a policy you've had for years, there's a much more useful question to ask:
What exactly am I trying to protect?
Don't confuse being insured with being protected
This distinction is really important.
You can have lots of insurance policies and still have gaps in your financial protection.
Equally, you might decide you don't need a particular type of insurance because you've already built other mechanisms that can protect you.
So rather than starting with the product, start with the risk.
Imagine you were diagnosed with a serious illness tomorrow.
What would actually happen financially?
Would you suddenly face enormous medical bills?
Would you be unable to work?
Would you need to replace your income for six months? A year?
Would there be additional expenses that aren't covered by your existing medical insurance?
Get really specific.
Because "I'm worried about getting seriously ill" is a fear.
"I need a way to replace eight months of income if I'm unable to work" is a financial problem you can actually plan for.
Some risks are simply too big to carry yourself
There are certain events where insurance can be incredibly important.
These are the big, catastrophic risks.
Your house is destroyed and needs to be replaced.
You end up in intensive care with enormous medical expenses.
Something happens where the financial cost is simply too large for you to comfortably absorb yourself.
Those are the risks we want to be very thoughtful about protecting.
When it comes to health, depending on where you live, that protection might come through medical insurance, medical aid, a hospital plan, gap cover or another appropriate form of medical cover.
The important thing is understanding which financial problem each piece of cover is solving.
Critical illness insurance usually does something different.
Rather than simply paying the medical expenses associated with your illness, it can provide a lump sum if you experience one of the qualifying events.
Which sounds reassuring.
But what are you going to use that lump sum for?
That's the question.
What job is that lump sum supposed to do?
Perhaps you're thinking:
If I get cancer and can't work for eight months, I need money to live on.
Fantastic. Now we have something tangible to work with.
How much would you actually need?
And what do you already have available?
Perhaps you've built an eight-month Cash Safety Net.
There's one layer of protection.
Perhaps your major medical expenses are already appropriately insured.
There's another.
Perhaps you have other assets you could access if necessary.
Another layer.
Suddenly, the problem looks very different.
You might discover that there is still a genuine financial gap that needs protecting.
Or you might discover that the thing you're paying an insurance company to protect you against is something you've increasingly built the ability to protect yourself against.
That's the difference between buying insurance because you're afraid and buying insurance because you've identified a genuine financial risk.
Your Cash Safety Net is a financial shock absorber
This is one of the reasons I'm such a fan of building a proper Cash Safety Net.
It's not just money sitting there doing nothing.
It's part of your protection system.
If you couldn't work for a period, your Cash Safety Net can help keep the lights on, food on the table, and your basic living expenses covered.
And as you continue building your net worth, your assets become another layer of protection.
Ultimately, this is one of the things we want our wealth to do for us.
Your assets aren't only there to fund your lifestyle. They're also there to help absorb life's expected and unexpected events.
They're your financial shock absorbers.
The stronger those shock absorbers become, the more your ability to self-insure certain risks can grow.
And this is something we work on throughout the Wealth Builders Club, not simply growing the biggest investment portfolio possible, but building all the different parts of your financial life so they work together.
Your money flow, Cash Safety Net, protection, investments and Financial Freedom Number aren't separate financial exercises. Together, they're what create a financial life that's increasingly able to handle both the things you're planning for and the things you absolutely aren't.
The closer you get to financial freedom, the equation changes
Think about someone at the very beginning of their wealth journey.
They rely completely on their salary.
They have very little saved.
If they're unable to work for six months, they have a serious financial problem.
Now imagine that same person years later.
They have a healthy Cash Safety Net.
They've built substantial investments.
Their major catastrophic risks are appropriately insured.
And they're getting closer and closer to their Financial Freedom Number.
Their assets are increasingly capable of supporting their lifestyle without them needing to work.
Do they necessarily need exactly the same insurance they needed twenty years earlier?
Not necessarily.
As your wealth grows, your need for certain types of insurance can change.
That doesn't mean you simply cancel insurance because you've accumulated some investments.
It means you keep reviewing the role each policy plays in your financial life.
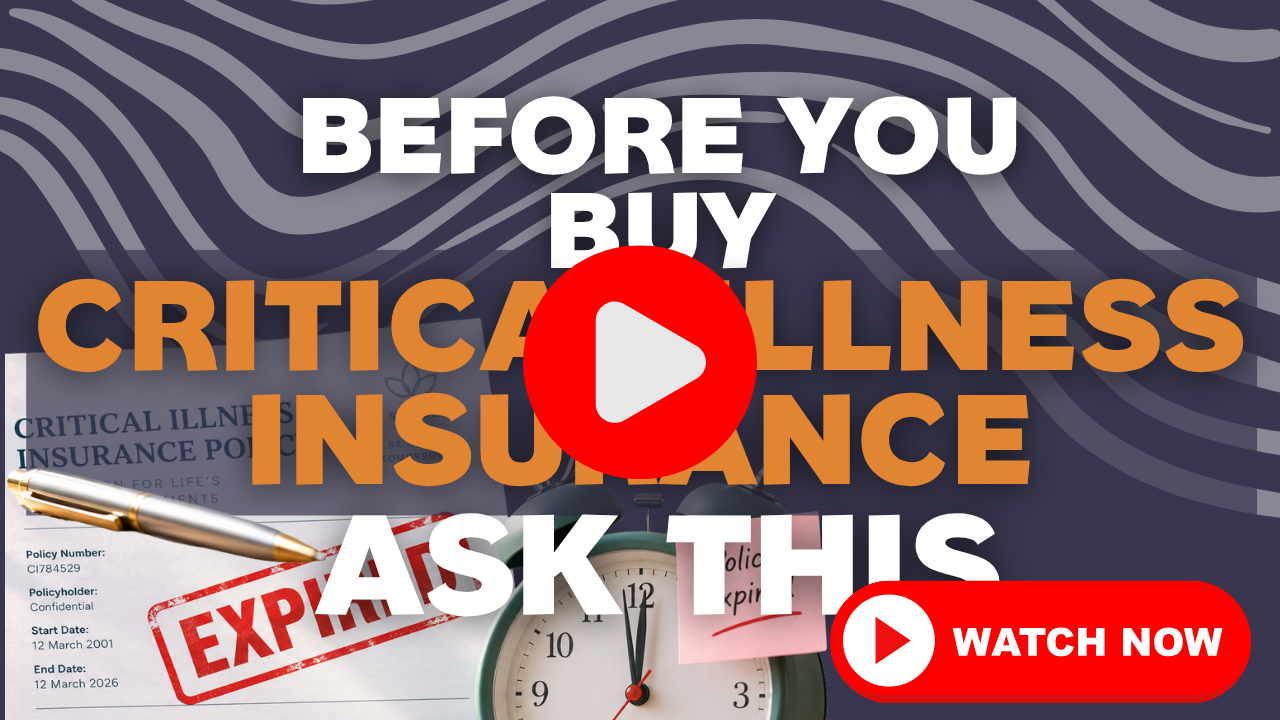
Know when your policies expire
There's another lesson here that is really easy to overlook.
You can pay for a policy for years, sometimes decades, and assume everything is ticking along nicely.
Then one month the debit order doesn't come off.
You investigate.
And discover that the policy has expired.
It was there in the small print all along.
Now you're older, and if you want to take out new cover, the insurer may assess and price that new policy based on where you are today.
That can be a nasty surprise.
So please don't treat insurance as a set-it-and-forget-it expense.
Know what you have.
Know what it covers.
Know what it doesn't cover.
Know what triggers the payout.
And know when it expires.
Your life changes. Your wealth changes. Your risks change.
Your insurance should be reviewed alongside them.
This is also why regularly reviewing your income statement and money flow is so powerful. A debit order can disappear into the background for years until you actually stop and look at where your money is going.
It's something MAPLE, our Money Flow Assistant, can help you do, bringing your income and expenses into view so you can spot those recurring costs and start asking, What am I paying for? Do I still need it? And is it still doing the job I originally bought it to do?
MAPLE isn't going to tell you which insurance you need. But she can help you see your numbers clearly enough to know which questions you should be asking.
Be very careful of fear-based financial decisions
Insurance deals with some of our deepest fears.
Cancer.
Disability.
Death.
Losing our income.
Not being able to provide for ourselves or our families.
That makes it very easy to sell insurance through fear.
But what if...?
It's a powerful question.
The problem is that there are an infinite number of frightening what ifs.
You can't build a sensible financial life by trying to insure yourself against every possible one.
Instead, slow down.
What am I actually afraid of?
If that happened, what would the financial consequence be?
What do I already have that would protect me?
What wouldn't be covered?
And where is the real gap?
The truth does set us free here.
Because once you replace a vague fear with actual numbers, you can make a far more informed decision.
Protection is part of building wealth
We spend a lot of time talking about growing wealth.
Investing.
Building assets.
Increasing our net worth.
Reaching our Financial Freedom Number.
But protecting what we're building matters too.
Because building wealth isn't simply about how much you can accumulate. It's about creating a financial life that becomes stronger and more resilient over time.
Your money flow.
Your Cash Safety Net.
Your assets.
Your protection.
Your Financial Freedom Number.
All of these pieces work together.
It's why, inside the Wealth Builders Club, we look at your whole financial picture rather than treating investing, protection and money management as completely separate things. The stronger each piece becomes, the more resilient your overall financial life becomes.
The goal is to reach a point where you're appropriately insured against the risks that could be financially catastrophic, while your own wealth increasingly gives you the ability to absorb the smaller bumps life throws your way.
Because real financial wellbeing isn't only about how quickly your wealth grows when everything goes right.
It's also about how well your financial life can absorb the moments when things go wrong.
Don't insure the fear. Protect the actual gap.
So if you're looking at critical illness cover, or any insurance, don't begin with:
What if something terrible happens?
Begin with:
If something happens, what specifically would put my financial wellbeing at risk?
Perhaps it's catastrophic medical expenses.
Protect those.
Perhaps it's losing your income for a period.
Work out how much you would need and what resources you already have.
Perhaps there are additional expenses your existing protection wouldn't cover.
Identify them.
Then look at the gap that's left.
Maybe insurance is the smartest way to fill it.
Maybe increasing another type of appropriate cover makes more sense.
Maybe your Cash Safety Net and assets mean you're increasingly able to self-insure some of that risk.
The answer won't be the same for everybody.
And that's precisely the point.
Your protection strategy should be built around your actual financial life, not around fear.
Know what you're protecting.
Know why you're protecting it.
And keep reviewing that answer as your wealth grows.
Because the ultimate goal isn't to own every insurance policy you possibly can.
It's to build enough protection, resilience and wealth that when life inevitably throws something unexpected your way, your financial world doesn't come crashing down with it.
That's what building real financial resilience looks like.
With love,
Ann x