The Debt BLITZ Method: A Step-by-Step Plan to Pay Off Debt
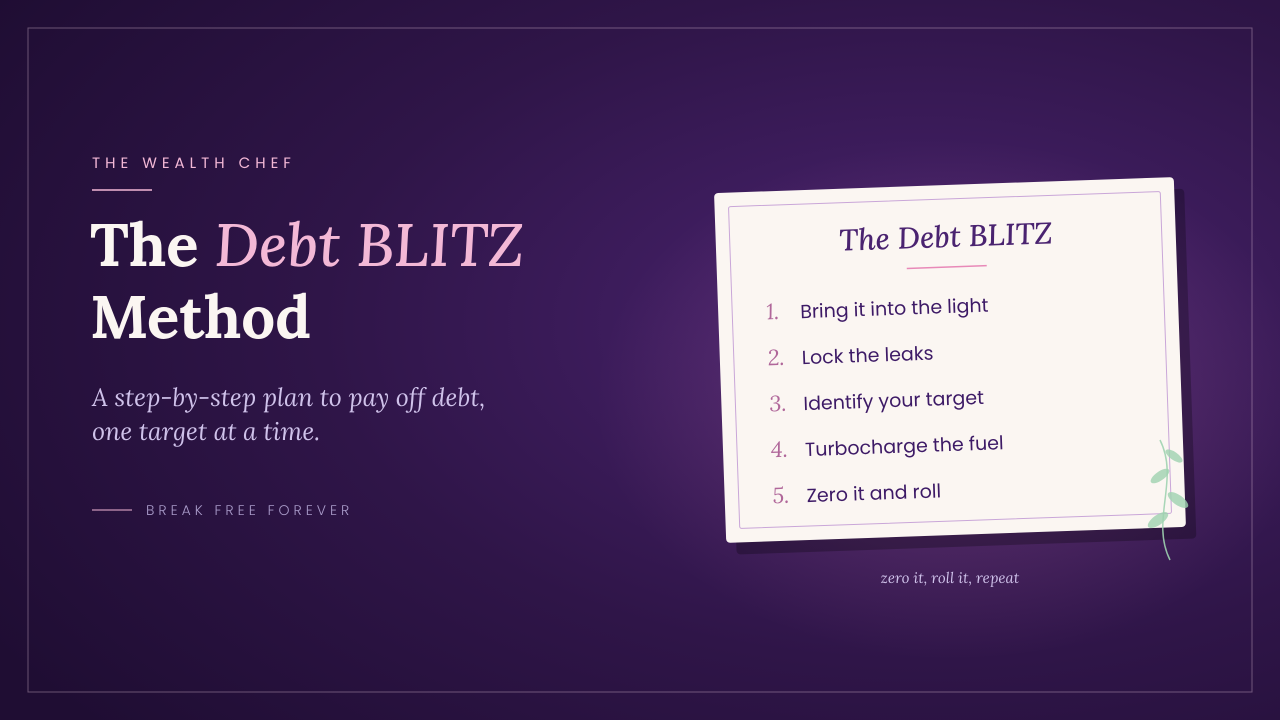
A step-by-step plan to pay off debt has three parts: see every debt clearly, keep every minimum payment going, then send all your extra money at one target debt until it hits zero and roll that payment onto the next. That's the Debt BLITZ, The Wealth Chef's get-out-of-debt method from my Break Free Forever book: Bring it into the light, Lock the leaks, Identify your target, Turbocharge the fuel, Zero it and roll. The debt snowball is used inside it.
This guide is part of my complete guide to getting out of debt and staying out.
For the deeper comparison of methods, read debt snowball vs avalanche, and why the BLITZ hybrid method beats both.
What is the Debt BLITZ method?
The Debt BLITZ is a five-step system for clearing consumer debt one debt at a time, with every spare pound focused on a single target. It isn't complicated. It's consistent.
| Step | What it means in practice |
|---|---|
| B: Bring it into the light | List every debt in one place, so nothing hides in the fog. |
| L: Lock the leaks | Find money leaking from your spending and redirect it. |
| I: Identify your target | Score your debts and put them in order, so you know exactly which one to attack first. |
| T: Turbocharge the fuel | Send as much extra as you can to that one target each month, on top of all your minimums. |
| Z: Zero it and roll | Clear the target, then roll its full payment onto the next debt. Repeat until you're free. |
The B starts with your Debt Truth Inventory: a list of every debt you owe with eight facts for each: balance, interest rate, minimum payment, term, special conditions, what you actually pay, why you took it on, and its emotional weight. Here's how to do your Debt Truth Inventory.
Before you start: three things to put in place
A BLITZ plan only works if your essential bills are covered, you have a small cash buffer, and no new debt is coming in.
1. Keep your essential bills paid
The BLITZ is for consumer debt: credit cards, store cards, overdrafts and personal loans. Your home, energy and tax bills come first. In the UK, MoneyHelper calls these priority bills, such as rent, mortgage, Council Tax and energy, because missing them can cost you your home or lead to legal action. Wherever you live, keep them paid before any extra goes to your BLITZ.
2. Build your Emergency Pot
Your Emergency Pot is about £800, $1,000, €1,000 or R10,000 in a separate account, built before the BLITZ, so a surprise bill never sends you back to credit. My own early attempts to get out of debt kept collapsing for exactly this reason. An unexpected bill arrived, I had no cash, and back onto the card it went.
3. Commit to no new consumer debt
Paying off debt while borrowing more is like bailing out a boat while someone pours water back in. The temptation usually turns up in one of three disguises:
- The emergency exception: "This time it's different." That's what the Emergency Pot is for. If it's empty, pause the BLITZ and refill it.
- The opportunity exception: "This course will pay for itself." If it's that good, it can wait.
- The lifestyle exception: "I've worked so hard, I deserve this." You do deserve good things. Bought with money you have, not borrowed from your future self.
How to build your BLITZ plan, step by step
Building your step-by-step plan to pay off debt takes six steps and one sitting. At the end you have your debts in order, a dated plan and a freedom date.
Step 1: Put your debts in BLITZ order
Your order comes from the BLITZ hybrid method, which scores each debt on interest rate (above 20% = 4, 10-20% = 3, below 10% = 2), balance size (below 10% of your total debt = 3, 10-30% = 2, above 30% = 1) and emotional weight (high = 2, moderate = 1, low = 0). The highest total goes first. Ties go to the smaller balance.
Step 2: Keep every minimum payment going
Every debt except your target keeps getting its minimum, unchanged. But minimums alone won't free you. That's the Minimum Payment Trap: minimum payments are set as a small slice of what you owe, so they shrink as your balance shrinks and barely reduce the debt. On a £3,000 card at 21%, the first minimum of about £82 includes about £52 of interest, so only about £30 comes off the debt.
Want to see it on your own numbers? Put one card, store account or loan into my free calculator.
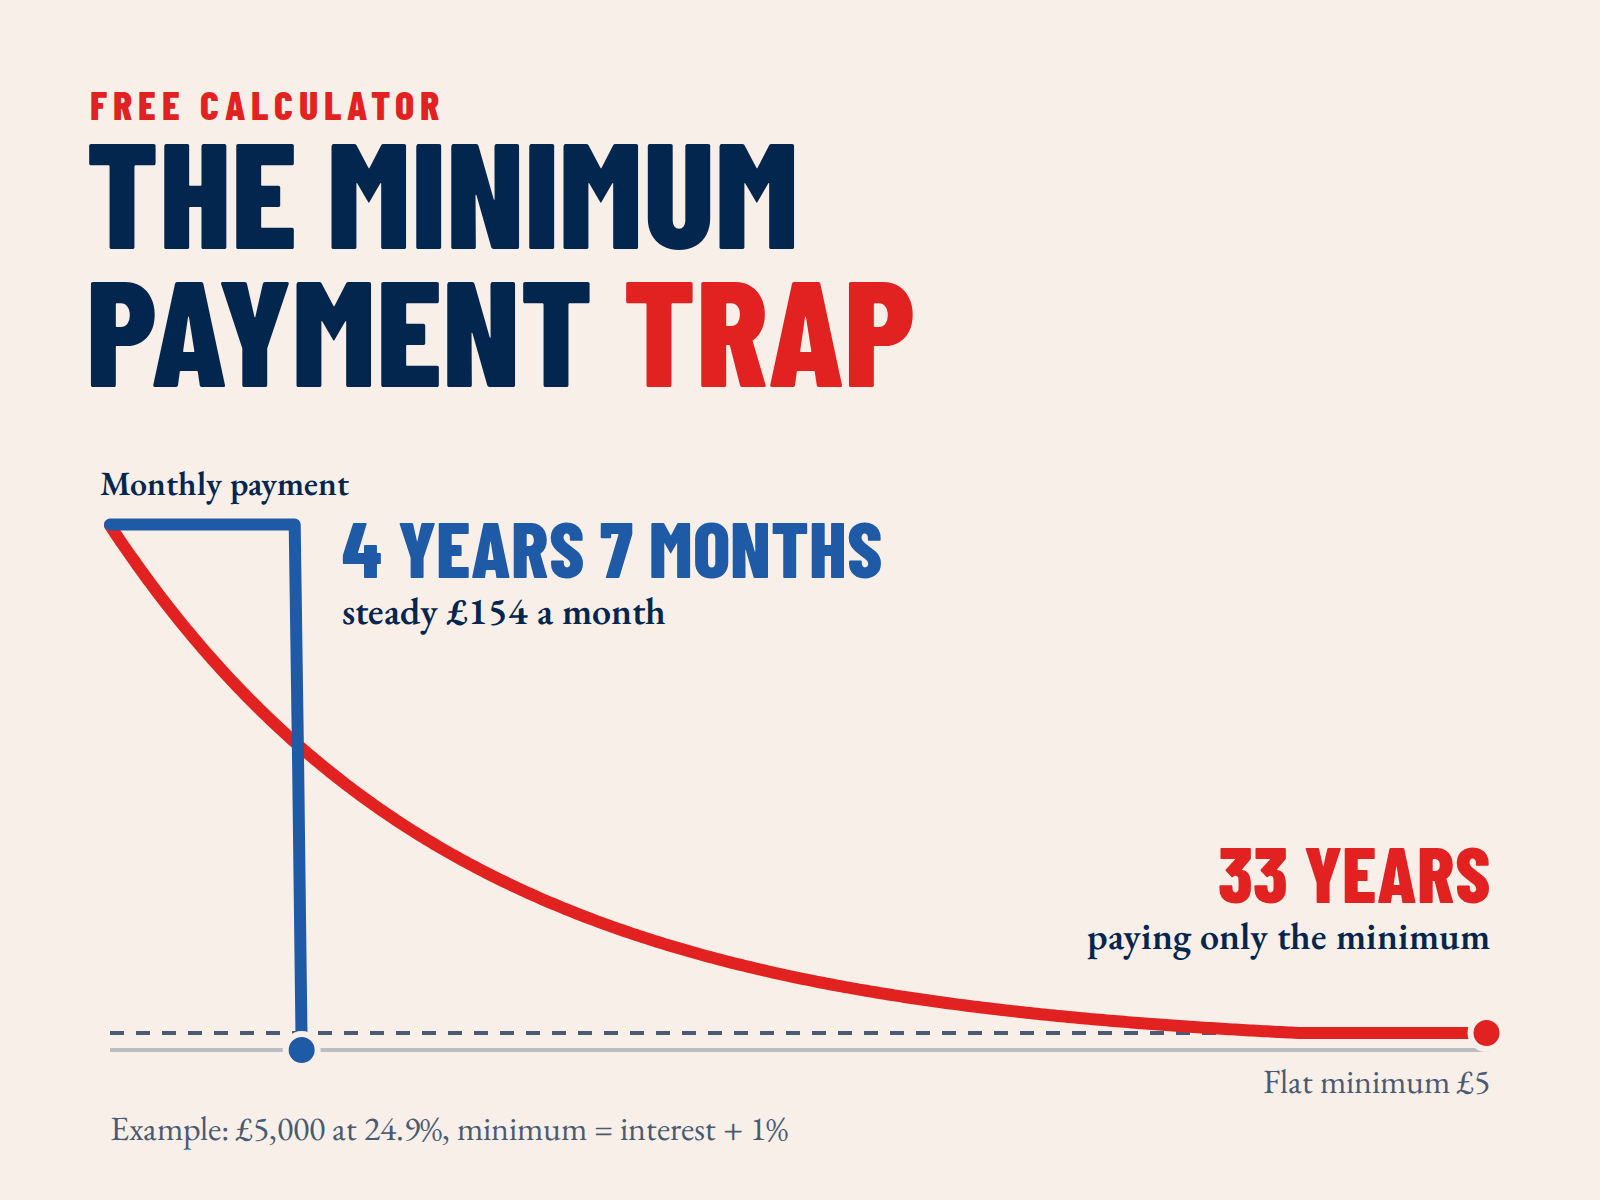
Try the free Minimum Payment Trap calculator
Step 3: Add your Debt Destroyer Fuel to debt number one
Your Debt Destroyer Fuel is the extra money each month, on top of all minimum payments, that goes to one priority debt at a time. Add it to your target debt's minimum. If the minimum on debt number one is £80 and your fuel is £200, you pay £280 a month to that debt.
Start with an amount you can commit to this month. It's better to commit to £100 and beat it than to commit to £300 and feel like a failure.
Step 4: Work out when debt number one falls
Put the balance, interest rate and your new monthly payment into a debt calculator and note the month it reaches zero. That's your first win date.
Step 5: Zero it and roll
When debt number one is gone, its full payment, the minimum plus your fuel, rolls onto debt number two, on top of that debt's own minimum.
Tania started her BLITZ with more than €10,000 of debt. When her first debt was cleared, she wrote: "Today I got confirmation that the first debt is repaid in full! So now I can use that money to chip away at the next one. If you're on the Blitz plan and it feels like you're not getting there yet, take heart: it happens sooner than you think, and it's such a weight off your mind when that debt is gone for good."
Step 6: Keep rolling to your BLITZ Freedom Date
Repeat the roll through every debt. The first debt is the slowest to fall and the last ones fall fast. The month your last debt hits zero is your BLITZ Freedom Date. Put it next to the date you'd have been free on minimums alone. The gap is years of your life, reclaimed.
A worked BLITZ plan: Emma's example
In a worked example from the book, Emma owes £13,400 across three debts and starts with £150 a month of Debt Destroyer Fuel. Her BLITZ clears it all in 40 months.
| BLITZ target | Monthly payment | Cleared |
|---|---|---|
| 1st: Store card £900 at 29% |
£24 minimum + £150 fuel = £174 |
Months 1 to 6 |
| 2nd: Credit card £4,500 at 21% |
£174 rolled + £80 minimum = £254 |
Months 7 to 28 |
| 3rd: Personal loan £8,000 at 9% |
£254 rolled + £180 payment = £434 |
Months 28 to 40 |
Emma pays about £2,870 in interest on her BLITZ. On minimum payments only, she would have taken more than 30 years and paid £24,771 in interest.
Turbocharge the fuel with a Wealth Leak Audit
Your starter plan uses the fuel you can commit to today. Your real plan uses what you find once you look for leaks, and that number is almost always bigger.
A Wealth Leak Audit is a check of six places money leaks out without you choosing it: convenience spending, subscriptions, lifestyle creep, emotional spending, social and obligation spending, and bank fees. People who expect to find £50 a month often find £200.
When Emma ran hers, she found another £100 a month. Her fuel rose to £250, her freedom date moved from 40 months to 28, and she saved a further £796 in interest. Here's how to find extra money to pay off debt with the Wealth Leak Audit.
Windfalls, setbacks and hard months
A BLITZ survives real life because it has a rule for each of the three things that usually derail a plan.
| When this happens | The BLITZ rule |
|---|---|
| A windfall arrives (bonus, tax refund, cash gift, something sold) |
It goes straight to your priority BLITZ debt. Not a treat. Straight to the debt. |
| An unexpected bill | Your Emergency Pot pays it. Pause the BLITZ for a month if you need to, refill the pot, then resume. |
| A hard month | Don't stop. Reduce the fuel if you must, but keep something extra going to your target. Don't break the chain. |
Consistency matters more than perfection. And if you can't cover even your minimum payments, don't push through alone: that's the moment to contact one of the free debt services listed below.
Questions people ask
What is the fastest way to pay off debt?
Aim every spare pound at one debt at a time while paying the minimum on the rest, and roll each cleared payment onto the next. In the US, the Consumer Financial Protection Bureau's guide to reducing debt describes the same one-target approach. The BLITZ adds emotional weight, so you stick with it.
Which debt should I pay off first?
Score each debt on interest rate, balance size and emotional weight, and start with the highest total. Essential bills like rent, mortgage, Council Tax and energy always come before any consumer debt.
What if I can only afford the minimum payments?
Start with a Wealth Leak Audit. If the minimums themselves are a struggle, get free help early, before you miss a payment.
Build your BLITZ plan free
ZARA is my free AI debt assistant. Tell her what you owe and she builds your Debt Truth Inventory with you, sets your BLITZ order and freedom date, and shows you what each extra pound a month buys in time and interest saved. Save your plan with your email at the end.
Build your BLITZ plan free with ZARA
The Break Free Forever book takes you through the full Debt BLITZ, including the emotional patterns underneath your debt, and shows you how to stay out for good once you're free.
If you're in serious financial difficulty, you don't have to work it out alone. Free, confidential help is available from StepChange, MoneyHelper or National Debtline in the UK, an NFCC-member non-profit credit counsellor in the US, or an NCR-registered debt counsellor in South Africa.
This article is for education only and isn't financial advice.
Written by Ann Wilson, founder of The Wealth Chef and author of The Wealth Chef and Break Free Forever. Debt-free since 1994 and financially free since 2006.